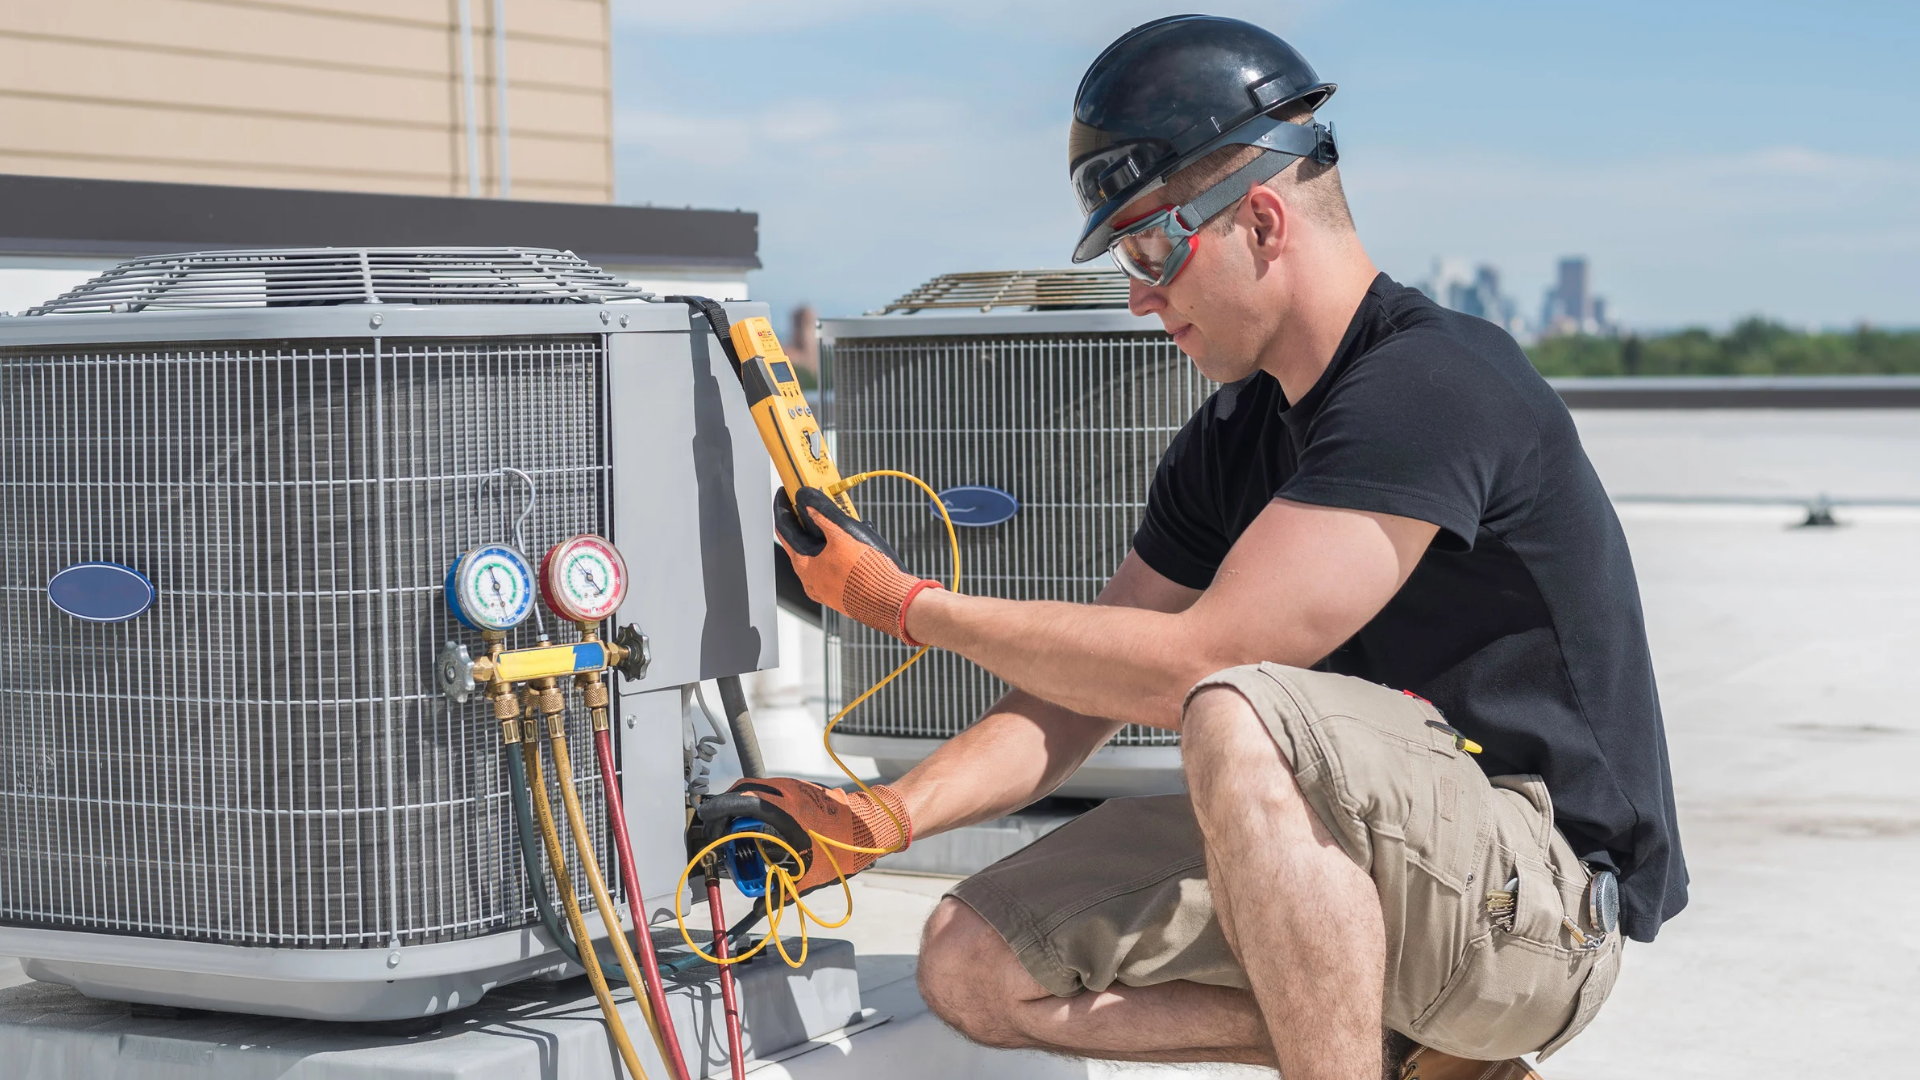
HVAC companies (Heating, Ventilation, and Air Conditioning) know that they provide a crucial service for both homeowners and businesses. These contracting companies keep the indoor temperatures comfortable for us all. However, all of this can come at a cost, should something go wrong with a job. Things like equipment losses, property damage, injuries, and accidents can occur, leaving your HVAC business exposed to liability.
Why Liability Coverage Matters for HVAC Contractors
There are a number of things that can go wrong on a job site that your business may be liable for. Incidents that cause property damage or physical injuries may be found to be your company’s fault. For example, if a furnace installation goes wrong and damages the home, or one of your customers trips and falls over some tools left at a job site, your company may end up having to pay the bills. Thankfully, your liability coverage will most likely help.
Remember that your standard business insurance covers your workshop and everything within, not accidents that occur on job sites.
Understanding Equipment Coverage
There’s a lot of tools used in the process of installing and repairing HVAC systems. Some of those tools are specialty items that cost quite a bit and are tricky to replace. Thankfully, there are insurance options for these situations that cover your tools and equipment.
Other Coverage HVAC Contractors May Need
In addition to your equipment coverage and liability policies, you may need a number of other relevant insurance options, like:
Workers’ Compensation – If you have employees, then you need to have workers’ compensation coverage. This type of insurance often pays for their missed work hours and medical bills should they get hurt on the job. It prevents your business from having to pay out of pocket for these things.
Commercial Auto Insurance – Businesses of all kinds, including HVAC contractors, need to have commercial auto insurance policies if their vehicles are driven for work purposes. If you only have a personal auto policy and get into an accident while driving for business reasons, your insurance may not cover the costs of repairs and more. Instead, you need to have a commercial auto policy.
Business Interruption Insurance – Your business relies on being able to get parts and equipment quickly. Should something happen to prevent this and cause delays, your company could suffer financial losses. There’s an insurance option for these situations, called business interruption insurance, which can help keep things afloat during tough times.
Inland Marine Coverage – Moving tools and equipment from place to place provides a number of opportunities for accidents that leave those crucial items out of service, making it difficult to complete your customer’s jobs. Inland marine insurance can help in these instances, providing coverage for new pieces of equipment and repairs to old ones.
These options all depend on the size and scope of your business, of course.
Contact Spivey Insurance
If your HVAC business needs additional liability or equipment coverage, reach out to Spivey Insurance. Our well-trained and knowledgeable agents can help you decide which policies and coverage amounts would be best for your company. Contact us today!